
Thursday, October 15, 2026

Alliance Resource Partners faces stranded asset risk as coal phase-out accelerates across four-state footprint

Alliance Resource Partners, L.P., the Tulsa-based coal MLP, confronts medium-probability catastrophic risk from energy transition rendering its Illinois, Indiana, Kentucky, and West Virginia mining complexes obsolete. The assessment carries 70% confidence as utilities accelerate coal plant retirements ahead of schedule. Stranded asset exposure threatens the partnership's debt service capacity and unitholder distributions.

Alliance Resource Partners faces stranded asset risk as coal phase-out accelerates across four-state footprint
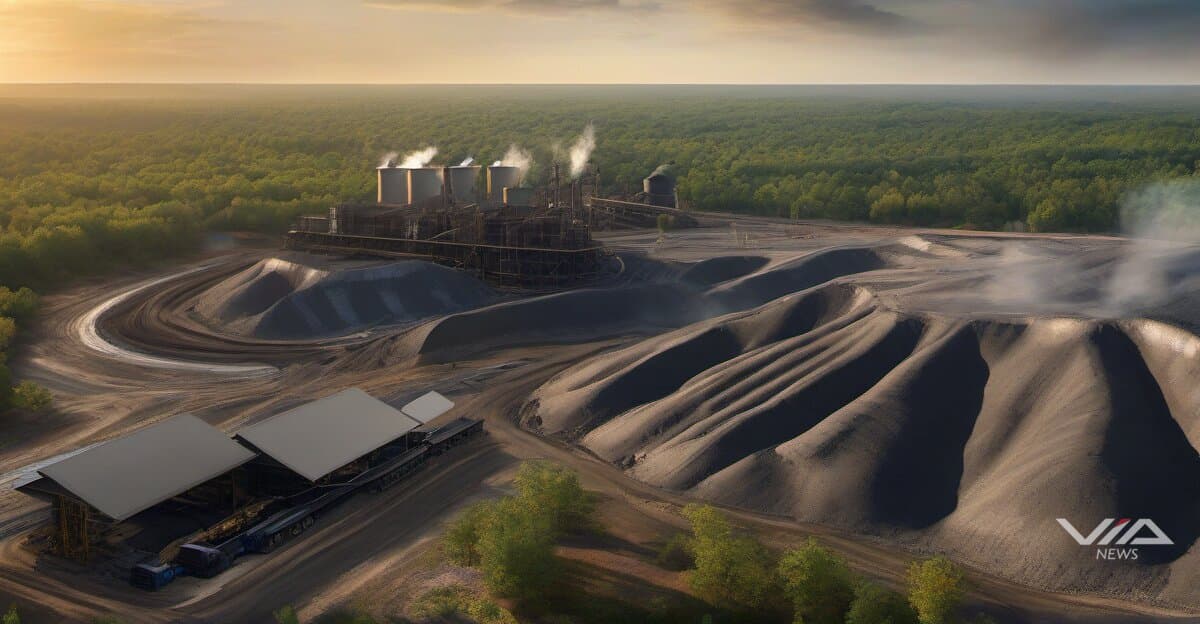
Image generated by AI for illustrative purposes. Not actual footage or photography from the reported events.

Alliance Resource Partners, L.P. faces catastrophic stranded asset risk across its mining complexes in Illinois, Indiana, Kentucky, and West Virginia as the energy transition accelerates faster than depreciation schedules assume.

The Tulsa-based master limited partnership produces, markets, and transports bituminous coal to electric utilities. Analysts rate the technological obsolescence risk at medium likelihood with 70% confidence, reflecting uncertainty around retirement timelines for coal-fired generation.

Coal plant retirements have accelerated beyond utility integrated resource plans filed three years ago. Natural gas prices remain structurally lower than 2010-2014 levels while renewable costs fell 90% for solar and 70% for wind since 2010. Battery storage deployment doubled annually from 2022-2025, enabling grid operators to replace coal baseload with renewable-plus-storage at lower all-in costs.

Alliance's MLP structure requires distributable cash flow to maintain unit prices and debt covenant compliance. The partnership carried $1.8 billion in long-term debt at last reporting. Asset impairments would reduce distributable cash flow while accelerated mine closures trigger reclamation obligations that compete with distributions.

The four-state operating footprint concentrates exposure. Illinois targets 100% clean energy by 2045. Indiana utilities retired 40% of coal capacity since 2020. Kentucky's two largest utilities announced coal phase-outs by 2035. West Virginia lost half its coal generation since 2010.

MLPs trade on distribution yield. Alliance's current distribution of $1.40 per unit annually yields 8-12% depending on unit price. Sustained distribution cuts typically trigger 30-50% unit price declines as income investors exit. Refinancing risk emerges if unit prices fall below debt covenant thresholds.

The partnership's coal reserves book at historical cost less depletion. Mark-to-market accounting would recognize stranded value immediately. Current GAAP treatment delays recognition until impairment tests trigger writedowns or mines close.

Investors face asymmetric risk. Upside scenarios require coal demand stabilization unlikely under current grid economics. Downside scenarios include accelerated closures, distribution suspensions, and potential bankruptcy if debt maturities coincide with cash flow deterioration.

What we know · the intelligence behind this page
Live from the substrate
What we're seeing
Q4 2026 Clinical Catalyst Season: Big-Pharma Data Flow, Regulatory Milestones, and a Thin AI-Drug Fringe
October 2026 conferences (EASD, IGCS, NACFC, HFSA) are producing a dense run of late-stage readouts from Novo Nordisk, Lilly, Roche, Bayer, Vertex and Galderma. Regulatory milestones are scheduled behind them: the ivonescimab BLA PDUFA date on 2026-11-14, FDA acceptance of Roche's vamikibart BLA, and Scholar Rock's EMA resubmission. The AI-and-finance angle is peripheral. It consists of the AI-designed drug Rentosertib and QAIAx, a speculative microcap whose trial claims (the QIII pilot, anticipated 2027-01-01, and a patent update) are forecasts and filings rather than data, so they warrant skepticism.
Our read on the data ›
Signals we're tracking
EPKINLY Regulatory-Clinical Success Cascade
High probability of expanded label indications, additional combination approvals, and competitive positioning strength in follicular lymphoma market. Predicts positive commercial uptake and potential accelerated review for related indications.
Patterns we're watching ›
Where sources disagree
ING Group
Both facts record the same metric (shares_outstanding) for ING Group at the identical observation date (2025-12-31). FACT A states 2,902,437,688 shares; FACT B states 2,902 million shares (2,902,000,000). The difference is 437,688 shares (~0.015%). This is a genuine value conflict, though the discrepancy appears to result from FACT B rounding to the nearest million while FACT A provides the precise count.
We flag conflicts openly ›
Recently verified
✓ Checked against the original source
4,986
facts traced to their source — and we flag the ones that don't hold up.
101 entities tracked4,986 facts checked against source5,375 source documents archived
Query this data → isubstrate.com